



Define the Plan as a Risk System
A complete futures trading plan is more than an entry signal. It must connect five components: strategy rules, position sizing, leverage limits, margin reserves, hedging decisions, and contingency procedures. The objective is not to predict every market event. The objective is to define what happens to the account when the trade works, when it fails normally, and when market conditions prevent an orderly exit.
Use one consistent unit of measurement. Dollar risk is usually the most practical because it allows comparison among price risk, margin requirements, account equity, and drawdown limits. For a futures contract, notional exposure equals futures price multiplied by the contract multiplier. Planned price risk equals stop distance multiplied by the multiplier and the number of contracts. These quantities are different: margin is collateral, not the maximum possible loss, while notional exposure measures market sensitivity rather than planned loss.
Assume a hypothetical $100,000 account trading E-mini S&P 500 futures at an index price of 5,000. The contract multiplier is $50 per index point, so one contract has $250,000 of notional exposure. The minimum tick is 0.25 index points, worth $12.50. All margin figures below are planning assumptions, not current exchange or broker requirements; actual requirements must be checked before each trading session.
Integrate Entry, Exit, and Position Size
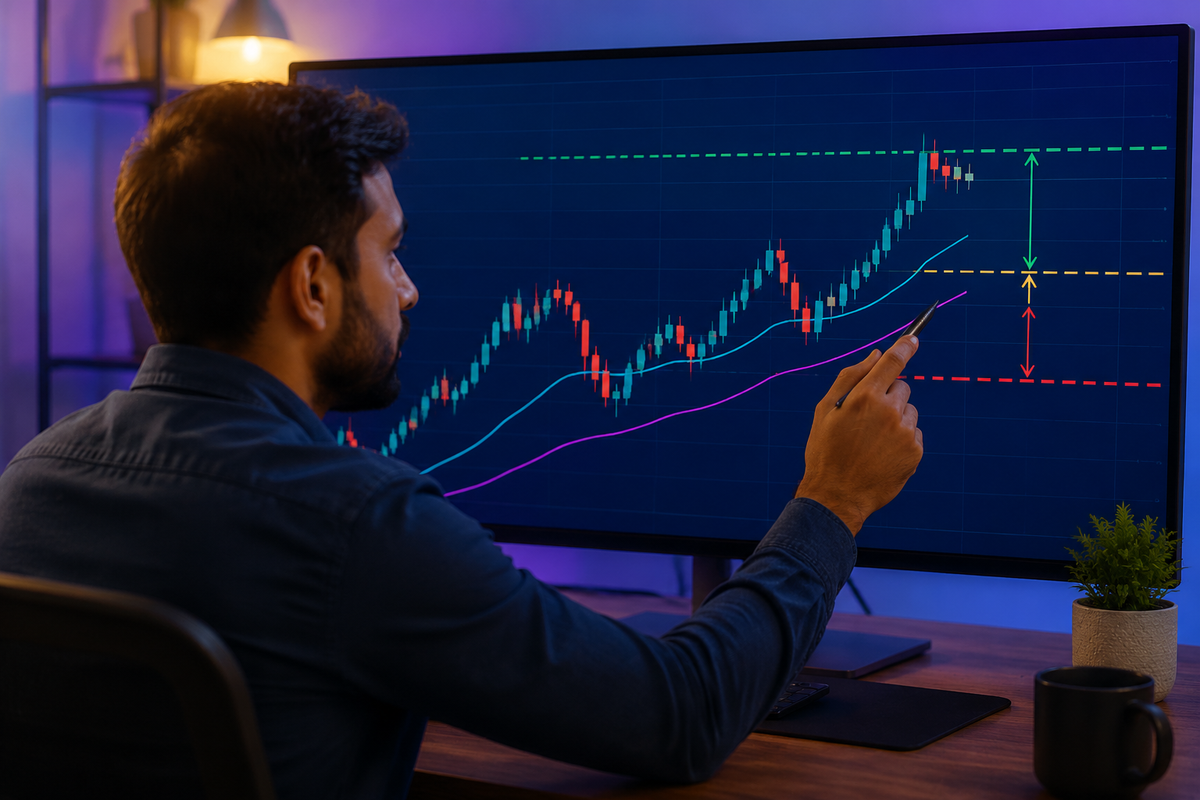
Consider a long trend-following setup with objective rules. Enter only after the daily close exceeds the highest close of the previous 20 sessions, the 20-day moving average is above the 50-day moving average, and current bid-ask spreads are within the plan’s normal range. Place the initial protective stop 30 index points below entry. Exit at the stop, after a close below the 20-day moving average, or after 15 sessions if neither a stop nor a trend exit occurs. Do not add contracts after entry unless pyramiding rules were tested separately.
At 5,000, the risk per contract from a 30-point stop is 30 × $50 = $1,500. Add four ticks of adverse slippage, equal to 1 point or $50 per contract, and assume $5 per contract for round-trip commissions and fees. Total planned risk is therefore $1,555 per contract. If the account-level risk limit is 2% of $100,000, the risk budget is $2,000. The allowed size is the whole number below $2,000 ÷ $1,555, which is one contract. Two contracts would create $3,110 of planned risk, or 3.11% of equity, and must be rejected even if the broker permits the order.
Define the profit-taking logic in advance. If the plan uses a fixed target of 60 points, the gross reward is 60 × $50 = $3,000 per contract. After the same $55 allowance for costs and slippage, approximate net reward is $2,945. The planned reward-to-risk ratio is $2,945 ÷ $1,555 = 1.89. This ratio does not prove profitability; it must be combined with the strategy’s tested win rate, loss distribution, and frequency.
Set Leverage and Margin Guardrails
With one contract, notional leverage is $250,000 ÷ $100,000 = 2.5 times account equity. Suppose the plan caps gross notional leverage at 3.0 times equity. The position passes. Two contracts would create $500,000 of exposure and 5.0 times leverage, so they would fail the leverage test independently of the risk-per-trade test. A position is allowed only if it satisfies every constraint, not merely the least restrictive one.
Assume hypothetical initial margin of $14,000 and maintenance margin of $12,700 per contract. The plan requires free cash after initial margin to remain at least three times maintenance margin. For one contract, free cash is $100,000 − $14,000 = $86,000, while the required reserve is 3 × $12,700 = $38,100. The account passes with a margin-reserve surplus of $47,900. This reserve is intended to absorb variation margin, margin increases, and execution delays; it is not permission to widen a stop.
The plan should also contain portfolio constraints. For example, total open-trade risk may not exceed 6% of equity, gross notional leverage may not exceed 4.0 times across all positions, and highly correlated equity-index positions may be treated as one exposure. If an existing Nasdaq futures position already consumes 3% of account risk, adding another 2% equity-index risk may satisfy the total limit but still violate a separate 4% correlated-risk cap.
Define Hedging Decisions Before the Event
A hedge should address a named temporary risk, not hide a trade that has invalidated its entry thesis. Suppose the account holds two E-mini contracts but faces a scheduled event during which the trader cannot monitor execution. One E-mini has the same index-point exposure as ten Micro E-mini contracts because the multipliers are $50 and $5. A 50% temporary hedge against two long E-mini contracts therefore requires ten short Micro E-mini contracts: two E-mini equivalents × 50% × ten Micro contracts per E-mini equivalent = ten.
The hedge ratio can be expressed as hedge notional divided by original notional. Ten short Micro contracts at 5,000 have notional exposure of 10 × 5,000 × $5 = $250,000. Two long E-mini contracts have $500,000 of notional exposure, producing a 50% hedge ratio. A 1% index decline would create an approximate $5,000 loss on the long position and a $2,500 gain on the hedge, before costs and basis differences, leaving a net loss near $2,500.
The plan must specify the hedge trigger, size, and removal condition. For example, apply the hedge 15 minutes before a named scheduled release only if the original trend signal remains valid, remove it within 30 minutes after spreads normalize, and exit the original position instead if its stop is reached. Include both legs in gross leverage and margin calculations. Hedging can reduce directional exposure while increasing transaction costs, operational complexity, and gross margin usage.
Run Quantitative Stress Tests
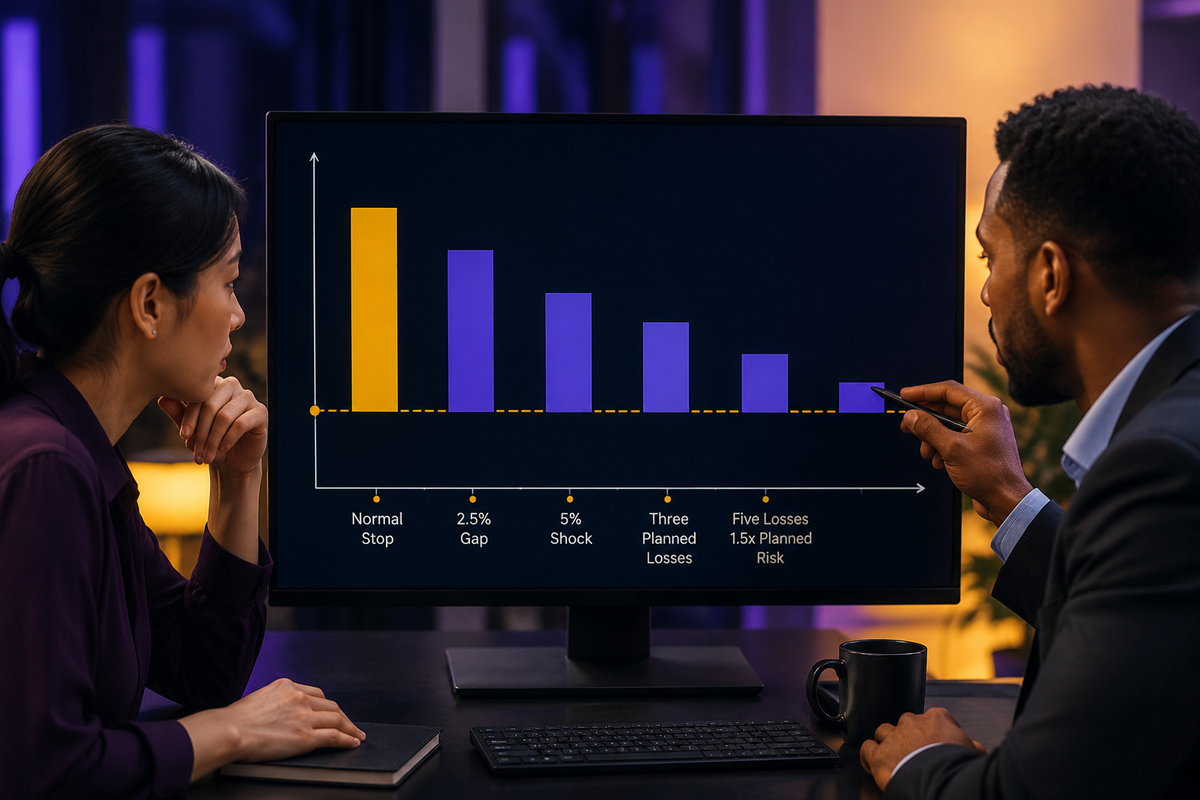
Begin with a gap-through-stop scenario. One contract entered at 5,000 has a stop at 4,970, but the market reopens at 4,875, a 2.5% decline. If execution occurs at 4,875, the loss is 125 points × $50 = $6,250, plus estimated costs. This is about 6.25% of the original account, over three times the planned 2% risk budget. The result demonstrates that a stop controls orders, not guaranteed execution prices.
Next combine price shock and margin shock. After the $6,250 gap loss, equity is approximately $93,750 before fees. If initial margin rises 60%, it increases from $14,000 to $22,400 per contract. Free equity after posting the new margin is $93,750 − $22,400 = $71,350. If the revised reserve rule still requires three times maintenance margin and maintenance also rises 60%, required reserve becomes 3 × $20,320 = $60,960. The account remains compliant, but the reserve surplus falls to $10,390. No additional position should be opened near that boundary.
Test a more severe 5% adverse move from 5,000 to 4,750. The one-contract mark-to-market loss is 250 × $50 = $12,500, reducing equity to approximately $87,500. Also test three consecutive planned losses: 3 × $1,555 = $4,665, or 4.665% of starting equity. Then test five losses with actual losses averaging 1.5 times planned risk: 5 × 1.5 × $1,555 = $11,662.50. The plan should pause new entries if drawdown reaches 10%, if realized slippage exceeds twice the tested assumption on three trades, or if margin reserve falls below its threshold.
Establish Contingencies and Approval Rules
Operational procedures must be explicit. If the trading platform fails, confirm position status through the broker’s independent channel and use the broker’s emergency order process if exposure must be reduced. If market data are stale or contradictory, do not initiate a new position. If the market is limit-locked and an exit cannot execute, cancel duplicate orders, preserve the intended exit order when appropriate, monitor exchange notices, and calculate exposure using the limit price rather than assuming the stop was filled.
Before entry, the plan is approved only when the signal is valid, planned risk is within the per-trade cap, aggregate risk and correlated risk are within limits, leverage passes, and the post-margin reserve remains adequate under the predefined margin shock. During the trade, position size cannot increase because of losses. After the trade, record intended and actual entry, stop, exit, slippage, fees, maximum adverse excursion, margin usage, and any procedural exception.
A robust plan is one that remains executable under stress, not one that merely reports an attractive backtest. If a scenario breaches the drawdown or liquidity tolerance, reduce contract count, select a smaller contract, increase cash reserves, or avoid the setup. The final decision rule is binary: trade only when every strategy, risk, leverage, margin, hedge, and contingency condition is satisfied.
Lesson Checkpoint
Review what you learned and get feedback on your work.