



Strategy Architecture
A rules-based directional futures strategy must convert market observations into decisions that another trader could reproduce without interpretation. The minimum components are a market and timeframe, directional filter, entry trigger, initial stop, profit exit, time exit, position-sizing rule, and conditions that prohibit trading.
Consider an illustrative E-mini S&P 500 futures strategy. One ES contract has a multiplier of $50 per index point and a minimum tick of 0.25 points, worth $12.50. The strategy uses completed daily bars for direction and 30-minute bars for execution. A long bias exists when the previous daily close is above the completed 50-day simple moving average. A short bias exists when it is below the average. Using only completed bars prevents look-ahead bias.
For a long trade, record the first regular-session 30-minute high and enter one tick above it. For a short trade, enter one tick below the first 30-minute low. Cancel an unfilled entry at 12:00 exchange time. Do not trade when the opening range exceeds 1.25 times the completed 14-day average true range, because an unusually wide range can produce an impractically distant stop. The exact session definition, data source, and contract rollover method must remain constant in research and live execution.
Risk, Stops, and Position Size
Define one unit of risk, or 1R, as the estimated loss if the initial stop is reached, including modeled slippage and commissions. Margin is not 1R. Margin is collateral required to hold the position, while market movement determines the loss. A position can satisfy margin requirements and still be too large for the strategy’s risk limit.
Suppose the account equity is $100,000 and the maximum risk per trade is 0.50%, so the risk budget is $500. A long entry fills at 5,205.25, and the objective stop is 5,197.25. The stop distance is 8.00 points. Gross risk per contract is 8.00 × $50 = $400. Assume two ticks of total adverse round-trip slippage, worth $25, and $5 of round-trip commissions and fees. Modeled risk per contract is therefore $400 + $25 + $5 = $430.
Position size equals the integer part of risk budget divided by modeled risk per contract. In this example, $500 ÷ $430 = 1.16, so the position is one contract. Two contracts would expose $860, or 0.86% of equity, and violate the 0.50% limit. If one contract exceeds the budget, the correct size is zero unless a smaller related contract has been explicitly tested.
At an entry of 5,205.25, one ES contract represents approximately 5,205.25 × $50 = $260,262.50 of notional exposure. Relative to $100,000 of equity, notional leverage is about 2.60 times. The trader must also confirm that available funds exceed the broker’s current initial margin requirement plus a predefined liquidity buffer. Margin requirements can change, so they must not be hard-coded from an old example.
Exits and Expected Value
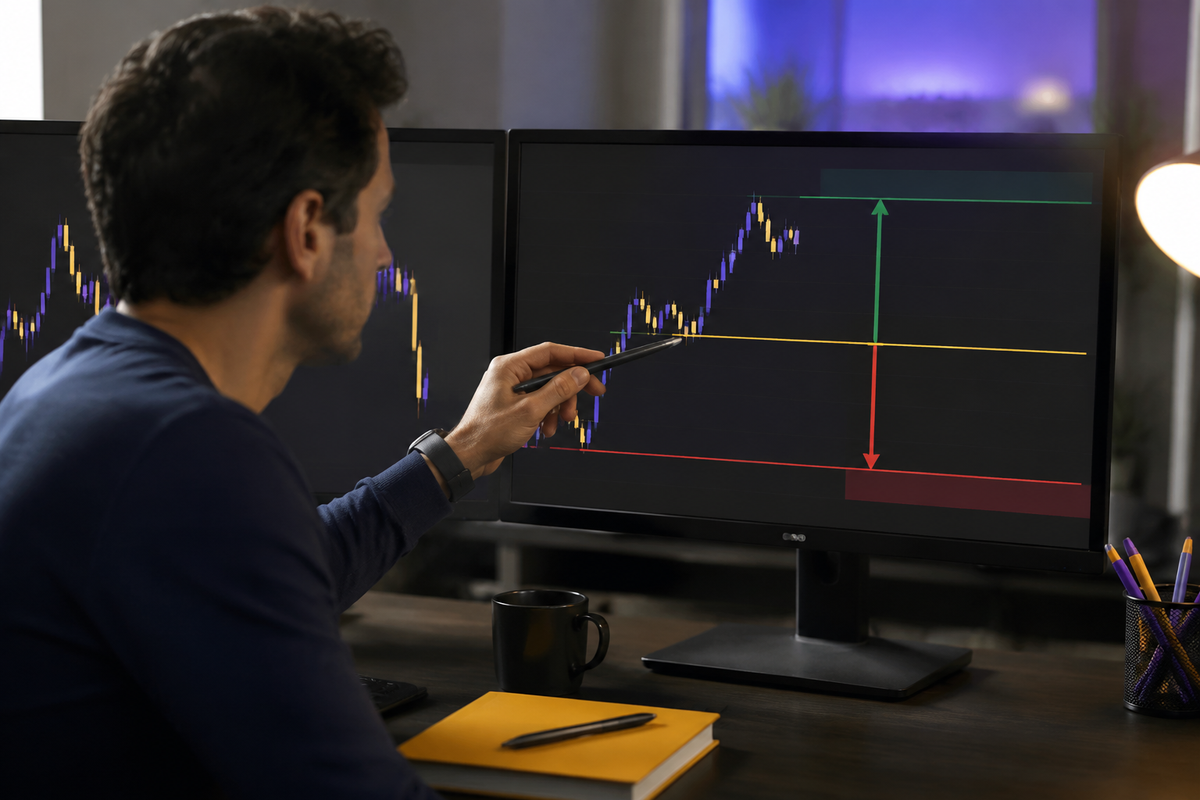
A nominal two-to-one target does not necessarily produce a net 2R payoff after costs. Here, modeled stop loss is $430. To achieve at least twice that amount after $30 of modeled costs, the gross target profit must satisfy target profit − $30 ≥ 2 × $430. The required gross profit is at least $890. Because ES moves in 0.25-point ticks, an 18-point target produces $900 gross and $870 net. The long target is therefore 5,205.25 + 18.00 = 5,223.25, giving a net reward-to-risk ratio of $870 ÷ $430 = 2.02.
Place the protective stop immediately after entry and never widen it. Move it only according to a rule tested in advance; otherwise, leave it unchanged. Exit at the target, at the protective stop, or five minutes before the regular-session close, whichever occurs first. A time exit prevents an intraday strategy from turning unintentionally into an overnight position.
Profitability depends on expectancy rather than one trade. If testing produces a 38% win rate, an average winner of 1.90R, and an average loser of 1.00R after costs, expectancy is 0.38 × 1.90R − 0.62 × 1.00R = 0.102R per trade. The break-even win rate is 1 ÷ (1 + 1.90) = 34.5%. These estimates are useful only if they come from enough observations across different volatility regimes and include realistic costs.
Execution and Validation Rules
Consistency requires explicit no-trade and shutdown conditions. Skip a setup if required margin plus the liquidity buffer exceeds available funds, market data are incomplete, the contract is inside the defined rollover window, the calculated size is zero, or the entry would occur after the cancellation time. Suspend new entries for the day after two stopped trades or a 1.0% daily equity loss, whichever comes first. A stop order limits intended risk but cannot guarantee the fill price during gaps or fast markets.
Record the signal time, bias, opening range, intended entry, actual fill, stop, target, size, margin available, slippage, fees, exit reason, and realized result in dollars and R. Evaluate the strategy with net expectancy, maximum drawdown, profit factor, consecutive losses, and rule-adherence rate. Test on historical data, reserve an out-of-sample period, and conduct simulated forward execution before risking capital. A strong process does not alter rules after isolated losses; revisions should follow a scheduled review using a meaningful sample and should be tested as a new strategy version.
Lesson Checkpoint
Review what you learned and get feedback on your work.