



Why Structure Matters
A structured market analysis process turns scattered information into a repeatable decision. The objective is not to predict every price move. It is to identify conditions in which expected reward is large enough relative to risk, while rejecting trades supported by only one attractive signal. Every analysis should produce one of three outputs: long candidate, short candidate, or no trade. No trade is a valid and often necessary conclusion.
Use a fixed analysis sequence so that recent news or a dramatic candle does not dominate judgment. A practical order is market regime, price action, technical confirmation, fundamental context, on-chain activity, sentiment, trade construction, and post-trade review. Complete the process at scheduled times, such as after each daily close for swing trading, rather than changing the method whenever the market becomes volatile.
Define the trading horizon before collecting data. A swing trader might use the weekly chart for regime, the daily chart for setup quality, and the four-hour chart for execution. Data should use matching observation windows whenever possible. Comparing a one-hour RSI reading with a 90-day fundamental trend without acknowledging the mismatch creates false precision.
Establish Regime and Price Structure
Begin with the broad market because most crypto assets are positively correlated during strong risk-on or risk-off periods. Measure the 30-day returns of Bitcoin, Ether, and the asset being studied. Then classify the regime using observable criteria. For example, an uptrend may require price above the 200-day moving average, a rising 50-day moving average, and a sequence of higher daily swing highs and lows. A downtrend has the opposite characteristics. If these conditions conflict, classify the regime as range-bound or transitional.
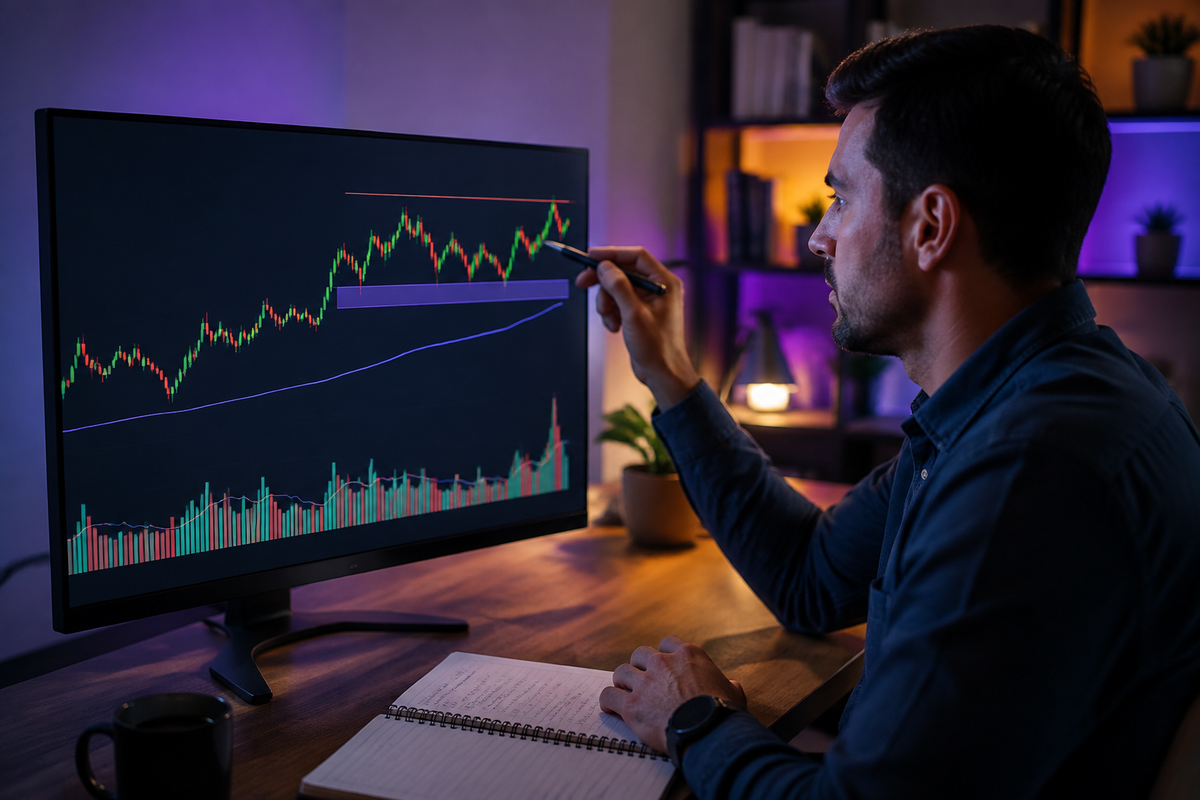
Mark structural levels before looking at oscillators. Identify the latest confirmed swing high, swing low, support zone, resistance zone, and high-volume consolidation area. A level is more useful when it has caused multiple reactions or coincides with a previous breakout. Measure distance rather than describing price as merely close to support. If an asset trades at $102 and support spans $96 to $98, the distance to the top of support is ($102 minus $98) divided by $102, or 3.92%.
Volatility determines whether that distance is meaningful. Suppose the 14-day average true range is $5. A $4 move to support equals 0.8 ATR, which can occur within normal daily variation. Normalize stops and targets with ATR or recent realized volatility instead of using the same percentage for every asset. Record whether volume expands on breakouts and contracts on pullbacks; a breakout with volume 1.8 times its 20-day average generally carries more evidence than one occurring at 0.7 times average volume.
Add Technical Confirmation
Technical indicators should answer specific questions rather than produce automatic trades. A moving average describes trend direction, ATR measures volatility, RSI summarizes recent momentum, and volume evaluates participation. Because price-based indicators often use the same underlying data, agreement between them is not fully independent. Price above a moving average and a bullish moving-average crossover may represent nearly the same evidence.
Create explicit thresholds before reviewing a setup. One example for a long swing candidate is daily close above the 200-day moving average, 20-day moving-average slope above zero, RSI between 50 and 70, and breakout volume at least 1.5 times the 20-day average. RSI above 70 is not automatically bearish, but it may indicate that entry risk is elevated after rapid expansion. Test thresholds on historical data and include fees and slippage before treating them as useful.
Look for contradiction as carefully as confirmation. A bullish breakout accompanied by declining volume, negative momentum divergence, and resistance less than one ATR above entry has weak trade geometry even if trend indicators remain positive. Indicators should modify confidence, not overrule invalid price structure. If the chart offers no logical invalidation point, the setup is not ready for risk calculation.
Evaluate Fundamentals and On-Chain Evidence
Fundamental research asks whether a catalyst or structural change can affect future demand and supply. Examine token issuance, unlock schedules, protocol revenue, active development, governance changes, security incidents, regulatory exposure, and product adoption. Convert headlines into measurable impact. If circulating supply is 500 million tokens and 50 million tokens unlock next month, the unlock equals 10% of current circulating supply. The next question is whether recipients can sell immediately and how that potential supply compares with average daily spot volume.
Use valuation ratios only when their definitions are consistent. A protocol with a $2 billion fully diluted valuation and $40 million annualized fee revenue has an FDV-to-fees ratio of 50. That figure becomes useful only when compared with the same protocol over time or with genuinely similar protocols. Fees are not automatically token-holder revenue, and temporary incentive-driven activity can inflate adoption metrics.
On-chain data can confirm or challenge the fundamental story. Relevant observations include active addresses, transaction count, transfer volume, stablecoin flows, exchange inflows and outflows, realized profit or loss, and holder distribution. Evaluate changes over stable windows, such as seven-day averages compared with 90-day baselines. If exchange inflows rise to two standard deviations above their 90-day mean, potential sell-side pressure deserves attention, but transfers between known exchange wallets may create a false signal. On-chain evidence must therefore be checked for entity labeling, chain coverage, and transaction context.
Measure Sentiment and Build a Score
Sentiment data helps identify crowded positioning. Useful measures include perpetual futures funding, futures basis, open interest, liquidation concentrations, put-call relationships, options skew, stablecoin demand, and survey or social indicators. For example, annualized funding of 25% combined with rapidly rising open interest and flat spot price suggests leveraged long demand without equivalent spot follow-through. That condition does not guarantee a decline, but it increases vulnerability to a long squeeze.
Combine the analysis with a transparent weighted score. One practical model assigns 30 points to regime and price structure, 20 to technical confirmation, 20 to fundamentals, 15 to on-chain evidence, and 15 to sentiment, for a maximum of 100. Score each category using predefined rules, not intuition after seeing the result. A trade might require at least 70 points, while any security exploit, unresolved data-quality problem, or inability to define a stop acts as a veto regardless of total score.
Assume a hypothetical asset receives 24 out of 30 for structure, 15 out of 20 for technicals, 12 out of 20 for fundamentals, 11 out of 15 for on-chain evidence, and 6 out of 15 for sentiment. Its total is 68, below the 70-point threshold, so the decision is no trade. The low sentiment score reflects crowded long positioning. This prevents strong price action from hiding derivatives risk and demonstrates why the process should not rely on a single bullish chart pattern.
Convert Analysis into a Trade Plan
A qualifying setup still needs defined entry, invalidation, target, position size, and maximum holding condition. Consider a hypothetical long entry at $100, a structural stop at $94, and a target at $115. Risk per unit is $100 minus $94, or $6. Potential reward is $115 minus $100, or $15. The reward-to-risk ratio is $15 divided by $6, or 2.5 to 1. Deduct expected costs when evaluating the setup. If combined fees and slippage equal $0.40 per unit, net reward becomes $14.60 and effective risk becomes $6.40, reducing the ratio to approximately 2.28 to 1.
Position size must follow account risk rather than conviction. With a $20,000 account and a 0.75% risk limit, maximum planned loss is $150. At $6.40 effective risk per unit, size is $150 divided by $6.40, or 23.43 units. Round down to 23 units, then verify that leverage, liquidity, and gap risk remain acceptable. A stop order limits normal execution risk but cannot guarantee the planned exit price during a sharp gap or exchange disruption.
Document the thesis and the evidence that would invalidate it. Review results in batches of at least 20 to 30 comparable trades rather than changing rules after one loss. Track win rate, average gain, average loss, expectancy, maximum drawdown, slippage, and performance by regime. If win rate is 45%, average win is 2.0R, and average loss is 1.0R, expectancy equals 0.45 times 2.0R minus 0.55 times 1.0R, or 0.35R per trade before costs. Sustainable analysis comes from consistent execution, calibrated risk, and evidence-based revision, not from adding more indicators.
Lesson Checkpoint
Review what you learned and get feedback on your work.